
A business can look busy, win new customers, and report a profit—yet still struggle to pay suppliers on time. This is not a contradiction. It is a cash-flow problem.
Imagine a consulting firm that invoices a large project in March, pays its team every two weeks, and does not collect from the client until June. Sales occurred. Revenue may even be recorded. But the bank account has to survive the gap.
When pressure builds, higher sales is often the instinctive answer. More sales can help, but they can also consume cash through inventory purchases, payroll, commissions, shipping, and longer customer payment terms.
Healthy cash flow comes from managing the timing and movement of money, not merely increasing the amount sold. The most useful improvements often begin inside operations, billing, purchasing, and planning.
💡 Start with the Meaning of Cash Flow
Cash flow is the movement of cash into and out of a business. It differs from profit, which is the accounting result after revenues and expenses are recognized under the applicable accounting method.
A profitable sale made on credit creates an account receivable, not immediate cash. Similarly, buying inventory may reduce cash immediately even though the related expense is recognized later, when the inventory is sold.
The practical question is simple: can the business meet its obligations when they fall due? Cash flow management is the discipline of making that answer reliably yes.
📊 Separate Profit from Liquidity
Liquidity is the ability to pay near-term obligations using available cash or assets that can quickly become cash. A company may be profitable on paper but illiquid if too much money is tied up in receivables or stock.
For example, a retailer may earn a healthy margin during a seasonal rush but run short of cash after placing a large order for next season. The income statement can look strong while the cash position weakens.
This distinction changes management decisions. A profitable opportunity is not automatically a cash-positive opportunity, especially when customers pay slowly or require customized work upfront.
🔄 Follow the Cash Conversion Cycle
The cash conversion cycle measures how long cash is committed to operating activities before it returns through customer collections. It broadly follows three stages: paying suppliers, holding inventory or delivering work, and collecting from customers.
Businesses generally improve operating cash flow by shortening the first-to-last journey: collect sooner, hold less unnecessary inventory, or obtain sensible payment terms from suppliers.
This is not about pushing every number to an extreme. A very small inventory buffer can create stockouts, and overly aggressive collection tactics can damage useful customer relationships. The aim is a cycle that fits the business model and risk level.
🧾 Invoice Immediately and Accurately
Many collection delays begin before an invoice is sent. Work may be completed, but someone waits for approval, searches for purchase-order details, or corrects an avoidable billing error.
Create a clear trigger for invoicing: shipment confirmation, completed milestone, signed timesheet, or accepted deliverable. Automate routine invoices where appropriate, but keep a review process for exceptions.
- Confirm the customer’s legal name, billing address, and tax information.
- Include the purchase-order number when the customer requires one.
- State payment terms, due date, bank details, and a contact for billing questions.
- Attach documentation that proves delivery or acceptance.
An invoice that is right the first time is easier for the customer to approve and harder for it to be delayed internally.
⏰ Make Payment Terms Match the Work
Payment terms should reflect the cash demands of the work. A business that must buy materials, reserve staff, or build a custom product before delivery should think carefully before offering long credit periods.
For a service project, a hypothetical structure might include a deposit before work begins, progress billings at agreed milestones, and a final invoice on completion. This reduces the chance that the supplier finances the entire project for the customer.
Terms must be commercially reasonable and clearly agreed. Changing them after work starts can create disputes, so discuss payment structure during quoting and contracting, not after the invoice is overdue.
💳 Offer Easier Ways to Pay
Customers may pay late because payment is inconvenient rather than because they lack funds. Electronic transfers, card payments, direct debit, and secure online payment options can remove friction from a routine process.
Each method has costs, settlement times, and fraud considerations. Card acceptance may involve fees, while direct debit requires proper authorization and careful handling of failed payments.
The right question is whether faster, more reliable collection is worth the processing cost for a particular customer group. For many small invoices, it can be.
📬 Build a Consistent Collection Routine
Collections work best as a normal administrative process, not as an emergency response. Send a courteous reminder before the due date, follow up promptly after it, and escalate consistently when accounts remain unpaid.
Assign ownership. If everyone assumes someone else will call the customer, overdue balances can remain untouched for weeks.
🗂️ A practical escalation path
- Send a friendly pre-due reminder with invoice details.
- On the due date, confirm that the invoice was received and approved.
- After the due date, call the appropriate accounts-payable contact and ask for a specific payment date.
- Escalate unresolved issues to the account manager or senior contact under a documented policy.
Keep notes on promises, disputes, and next actions. A receivables list becomes far more useful when it explains what will happen next.
🔎 Investigate Disputes Before They Age
An unpaid invoice is not always a collection failure. It may reflect a missing document, price discrepancy, damaged shipment, incomplete work, or customer approval problem.
Separate disputed invoices from invoices that are simply unpaid. Then identify the cause and owner of each dispute. A sales representative may need to confirm scope; operations may need to provide proof of delivery; accounting may need to issue a corrected invoice.
Fast resolution protects cash and reveals process weaknesses. Repeated disputes around the same item, service, or customer often signal a problem that starts before billing.
🤝 Screen Credit Before Extending It
Offering credit is a business decision, not merely a sales courtesy. Before granting substantial terms to a new customer, consider their payment history where available, order size, financial signals, industry conditions, and the consequences if payment never arrives.
Credit limits can prevent one customer from absorbing a disproportionate share of working capital. A limit is not a judgment of the customer’s character; it is a control over the business’s exposure.
Use a documented approval process for exceptions. Sales teams need flexibility, but managers also need visibility when commercial promises create unusual collection risk.
📦 Reduce Inventory Without Creating Stockouts
Inventory is often necessary, but it is also cash waiting to become a sale. Excess quantities, slow-moving items, duplicates, and obsolete products can quietly absorb capital and storage space.
Review inventory by movement and margin, not only by total value. An item that sells steadily may deserve reliable replenishment; an item that has not moved for a long time may need a different purchasing strategy, promotion, return arrangement, or write-down assessment.
Cutting inventory blindly can be costly if customers cannot obtain core products. The goal is better inventory quality: enough of the right items, not simply less of everything.
📈 Improve Demand and Replenishment Planning
Better purchasing begins with better visibility. Compare expected demand with open customer orders, seasonal patterns, supplier lead times, and current stock already committed to orders.
Even a simple rolling forecast can reduce panic buying and duplicate orders. Update it often enough to reflect material changes rather than treating an annual budget as a fixed operational plan.
Where demand is uncertain, smaller and more frequent orders may protect cash, although they may raise freight costs or lose volume discounts. Evaluate the total trade-off rather than focusing on unit price alone.
🏷️ Convert Slow Stock into Usable Cash
Slow-moving inventory deserves an active decision. Holding it indefinitely can make financial reports look less painful in the short term while cash remains trapped and the item becomes harder to sell.
Possible responses include bundling, targeted discounts, selling through alternative channels, returning eligible goods, repurposing components, or discontinuing further purchases. The best option depends on brand position and recoverable value.
A discount can reduce gross margin, but it may still improve overall cash availability compared with continued storage, handling, and eventual obsolescence. Measure the decision against realistic alternatives, not the original purchase price alone.
🤝 Negotiate Supplier Terms Thoughtfully
Supplier payment terms influence the timing of cash outflows. Longer terms can relieve pressure, particularly when they align with the time needed to sell stock or collect from customers.
However, terms are part of a relationship. Deliberately paying beyond agreed dates may lead to supply interruptions, lost discounts, tighter credit, or damaged trust.
Better approaches include discussing planned order volumes, consolidating purchases, agreeing staged payments, or asking for terms that reflect a predictable operating cycle. A supplier is more likely to cooperate when communication happens before a crisis.
🏷️ Evaluate Early-Payment Discounts Carefully
An early-payment discount can be attractive, but it is not automatically the best use of cash. Paying sooner reduces cash on hand, so the decision should consider the discount size, available liquidity, and alternative uses for the money.
For example, taking a discount may be sensible when cash is comfortably available and the saving is meaningful. It may be unwise if paying early would prevent payroll or force expensive short-term borrowing.
Record discount opportunities and review them systematically. Missing favorable terms through administrative oversight is different from deliberately preserving cash.
✂️ Control Spending at the Commitment Stage
Cash is often committed before an invoice arrives. A manager approves a subscription, signs a purchase order, renews a service contract, or authorizes overtime; the later payment is merely the final step.
Use purchase approval thresholds that fit the organization’s size. The aim is not bureaucracy for minor necessities, but visibility for commitments that could strain a budget or duplicate an existing service.
Ask three questions before approving discretionary spending: Is it needed now? Is there an existing alternative? What cash obligation does it create over the next few months?
🧹 Remove Recurring Cost Leakage
Recurring expenses are easy to overlook because each charge may seem small. Unused software seats, auto-renewing services, unnecessary delivery upgrades, redundant insurance features, and outdated vendor arrangements can accumulate.
Review recurring payments by owner, purpose, renewal date, and cancellation terms. If no employee can explain the business purpose, investigate before renewing.
Cost reduction should not mean cutting controls, maintenance, training, or customer support that prevents much larger costs later. Distinguish low-value leakage from spending that protects operations.
🧮 Price for Cash Requirements, Not Only Margin
A product can have a positive accounting margin yet impose substantial cash strain. This happens when materials are purchased well before sale, customers pay late, returns are high, or the work requires extensive labor before billing.
When pricing a contract, include the timing of cash costs as well as direct costs and desired margin. Deposits, milestones, minimum order sizes, and change-order policies can be as important to cash flow as the headline price.
This does not mean every customer should receive the same structure. It means commercial terms should reflect the economics and risk of the particular work.
🛠️ Use Deposits and Progress Billing for Long Jobs
Long projects are especially vulnerable to cash gaps. A construction contractor, designer, manufacturer, or software implementation team may incur months of labor and materials before the final handover.
Deposits and progress billing divide the project into financeable stages. Typical milestones might be design approval, material procurement, prototype acceptance, delivery, or implementation completion.
Milestones should be objective, clearly documented, and agreed in advance. Vague billing triggers invite disagreements precisely when the business needs cash most.
👥 Align Sales Incentives with Collection Quality
If sales compensation rewards only signed orders or invoiced revenue, teams may have little reason to care whether customers pay on time. That can encourage weak credit decisions or concessions that shift financing burden to the business.
A balanced approach may consider collected revenue, overdue balances, margin quality, or approval of nonstandard terms. The exact design should be transparent and should not punish staff for issues outside their influence.
Finance and sales do not need opposing goals. Both benefit when customers are profitable, satisfied, and able to pay under clearly understood terms.
📅 Create a Rolling Cash Forecast
A cash forecast estimates future inflows and outflows over a defined period. It is not a prediction of perfection; it is an early-warning tool that turns uncertainty into visible assumptions.
Start with bank balances, expected customer receipts by likely date, payroll, taxes, debt payments, supplier invoices, rent, and known capital spending. Then update the forecast as new information arrives.
A rolling forecast is more useful than a one-time document because it continually extends forward. It helps managers see whether a shortfall is approaching early enough to collect faster, defer spending, negotiate terms, or arrange financing responsibly.
🧭 Use Scenarios Instead of One Optimistic Plan
Customer payment dates are uncertain, especially for large invoices. Build a base case, a cautious case with slower receipts or higher costs, and an upside case where expected collections arrive as planned.
Scenario planning does not require complicated software. Its value comes from asking: what changes if the largest customer pays thirty days late, a shipment is delayed, or a major repair becomes necessary?
Pre-agree practical responses to each scenario. Decisions made calmly before a shortfall are usually better than decisions made after the bank balance has become urgent.
🏦 Treat Financing as a Tool, Not a Substitute
Overdrafts, lines of credit, invoice financing, and term loans can bridge legitimate timing gaps. They may be appropriate when cash needs are temporary, predictable, and supported by a credible repayment source.
Financing does not fix a structurally unprofitable product, chronic late billing, or customers who do not pay. It can conceal those problems while interest, fees, and repayment obligations grow.
Terms, security requirements, covenants, and personal guarantees vary substantially. Businesses should understand the full obligation and seek qualified financial or legal advice when the decision is material or complex.
🧾 Understand Taxes and Other Fixed Obligations
Some cash outflows are easy to underestimate because they are not ordinary supplier invoices. Payroll-related obligations, sales taxes collected on behalf of authorities, income tax payments, insurance premiums, and debt installments can create sharp cash demands.
Money collected for taxes is generally not operating cash available for expansion. Set it aside or reflect it explicitly in the forecast so a busy sales month does not produce a surprise liability later.
Payment rules vary by jurisdiction and entity type. Confirm applicable requirements with a qualified adviser rather than relying on a generic schedule.
📏 Track a Small Set of Useful Measures
Metrics should prompt action, not create reporting for its own sake. Choose measures that show where cash is being delayed or consumed.
| Measure | What it indicates | Useful management question |
|---|---|---|
| Accounts receivable aging | How long invoices remain unpaid | Which balances need follow-up or dispute resolution? |
| Days sales outstanding | Average collection speed | Are customers taking longer to pay than expected? |
| Inventory turnover | How often stock is sold and replenished | Which categories are tying up cash? |
| Cash forecast variance | Difference between expected and actual cash movement | Which assumptions repeatedly prove unreliable? |
Interpret trends alongside context. A temporary increase in receivables may reflect a large, creditworthy customer invoice; a persistent increase may signal weakened collection discipline.
🧩 Connect Operations, Sales, and Finance
Cash flow is not owned by accounting alone. Operations controls delivery evidence, purchasing controls inventory commitments, sales negotiates terms, and finance monitors invoices, payments, and forecasts.
Regular cross-functional review can surface issues early: a customer has not approved a milestone, a supplier changed lead times, a large order requires an unusual deposit, or a contract includes a billing clause that is difficult to administer.
Shared visibility turns cash management from a month-end cleanup task into an operating habit.
⚠️ Avoid False Cash-Flow Fixes
Some actions improve cash briefly while creating larger problems. Delaying essential maintenance, stopping all hiring despite critical capacity needs, pressuring reliable suppliers unfairly, or heavily discounting profitable products can weaken the business.
Likewise, collecting customer deposits without having the capacity to deliver can create a future obligation rather than a durable improvement. Cash received is not automatically cash earned or freely spendable.
A sound decision improves timing while preserving the company’s ability to serve customers, meet obligations, and remain credible.
🧪 Run a 30-Day Cash Improvement Review
A focused review can reveal practical opportunities without requiring a major transformation. Start with the largest and most immediate balances rather than trying to optimize every process at once.
- List all overdue receivables and assign a next action and owner.
- Identify invoices that can be issued this week but have not yet been sent.
- Review the next month of supplier payments, payroll, taxes, and debt obligations.
- Pause or question discretionary commitments that do not support near-term operations.
- Review slow inventory and open purchase orders for items that are no longer needed.
- Update the rolling forecast after each major collection or spending decision.
The purpose is not to create a one-time cash scramble. It is to establish information and routines that prevent the next scramble.
🎯 The Core Principle: Improve the Timing of Money
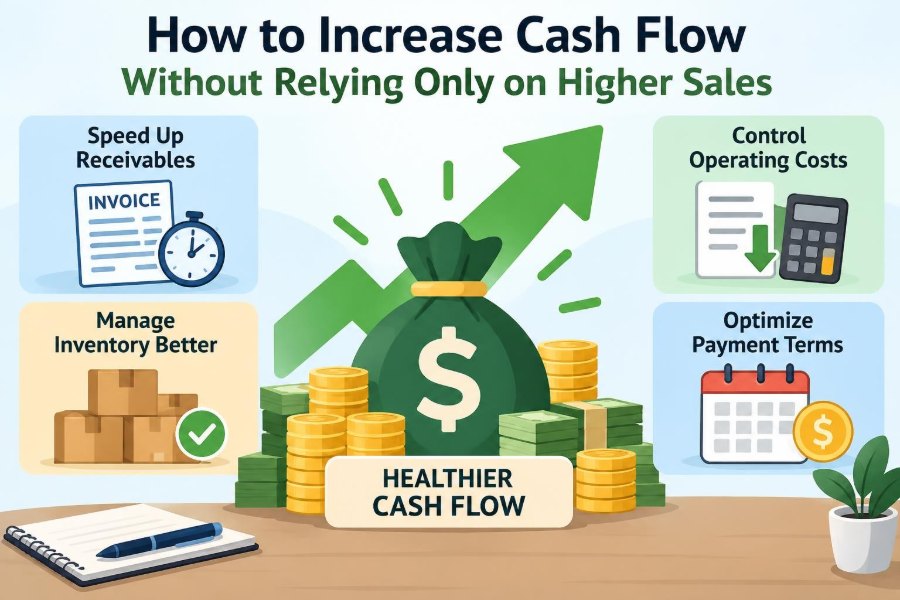
Increasing cash flow without relying only on higher sales usually means improving the interval between paying out cash and receiving it back. Faster accurate billing, disciplined collections, sensible inventory levels, aligned supplier terms, controlled commitments, and realistic forecasting all work on that interval.
No single lever fits every business. A subscription company may focus on billing and payment failures; a manufacturer may focus on inventory and supplier schedules; a project business may gain most from deposits and milestone invoices.
The common thread is deliberate design. Cash flow improves when commercial promises, operating processes, and payment timing are managed as one connected system.
Higher sales can strengthen a business, but they are most valuable when the business can convert those sales into cash predictably. Build that capability through clear terms, reliable processes, and regular forward-looking review. 💰📈🤝