
A business can feel busy, successful, and cash-generative while quietly earning very little from its best-known customers or most popular offerings.
Imagine a company that celebrates a large customer contract, only to discover that the customer requires constant support, rush deliveries, custom reporting, and unusually generous payment terms. Revenue looks impressive. Profit does not.
The same problem appears with products. A fast-selling item may consume expensive materials, create high return rates, or occupy valuable production capacity that could have been used for a stronger-margin alternative.
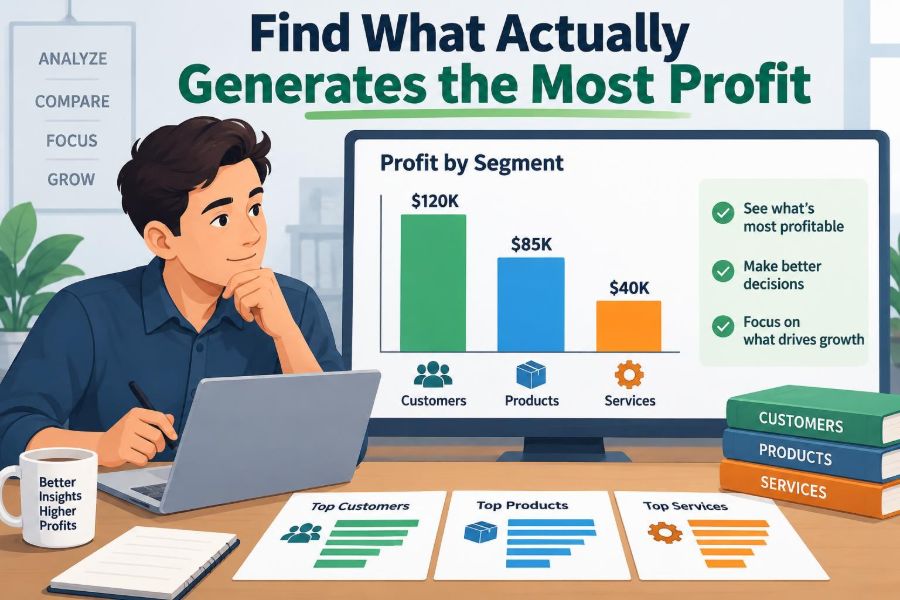
Finding what is actually profitable means moving beyond sales totals and asking a more useful question: after the costs caused by a specific customer, product, or service, how much does the business truly keep?
🔍 Start With the Difference Between Revenue and Profit
Revenue is the amount billed or earned from sales. Profit is what remains after relevant costs are deducted. The two measures answer different questions.
A customer that spends $100,000 is not automatically more valuable than one that spends $40,000. If serving the first customer costs $95,000 while serving the second costs $20,000, the smaller account contributes more profit.
Revenue is useful for measuring market demand and business scale. Profitability analysis is useful for deciding where management attention, capacity, pricing effort, and investment should go.
💡 Define the Profit Question Before Pulling Data
“Which customer is most profitable?” sounds straightforward, but it can mean several things. A business should define the question before building reports, because each version requires a different set of costs.
- Which customer produces the highest gross profit?
- Which customer generates the highest profit after sales and service costs?
- Which product has the best profit per unit?
- Which service produces the best return per staff hour?
- Which account is most profitable after considering credit risk and capital tied up in receivables?
There is no universally correct measure. The best measure is the one that supports the decision being made.
🧾 Build a Reliable Revenue Base
Profitability analysis begins with accurate, consistently classified revenue. This sounds basic, but it is common for customer reports to include cancelled orders, unearned deposits, sales tax, internal recharges, or estimates that should not be treated as operating revenue.
Use the revenue recognition approach appropriate to the business and apply it consistently across customers, products, and service lines. A comparison is meaningful only when each item is measured on the same basis.
Also record sales allowances, rebates, promotional discounts, credits, and returns separately. A customer with high list-price sales may have much lower net revenue after those reductions.
🏷️ Calculate Gross Profit First
Gross profit is usually calculated as net revenue minus the direct cost of producing or acquiring what was sold. For a retailer, direct cost often includes the purchase cost of inventory. For a manufacturer, it may include materials and direct production labor.
For a consulting firm, direct costs may include payroll and benefits for staff who worked on the engagement, subcontractor fees, and directly attributable travel.
Gross profit is a useful first screen because it identifies whether sales are covering their immediate delivery costs. It is not, however, the final answer for customer or service profitability.
📊 Use Margin Percentages Alongside Dollar Profit
A dollar figure and a percentage reveal different things. Gross profit dollars show how much money an item contributes. Gross margin percentage shows how efficiently revenue turns into gross profit.
For example, a product selling for $1,000 with a direct cost of $700 generates $300 of gross profit and a 30% gross margin. A product selling for $300 with a direct cost of $150 generates $150 and a 50% margin.
The first product contributes more dollars per sale; the second retains more of each sales dollar. Capacity constraints, working capital needs, and growth plans determine which measure matters more in a particular decision.
🧮 Separate Direct Costs From Shared Costs
A cost is direct when it can be traced to a specific customer, product, job, or service without unreasonable effort. It is shared when it supports multiple activities at once.
Direct costs might include a project-specific subcontractor invoice, product packaging, sales commission tied to one order, or a dedicated account manager. Shared costs might include executive salaries, office rent, accounting software, and general marketing.
This distinction matters because forcing every overhead cost onto individual customers can create a false sense of precision. First determine the costs genuinely caused by the customer or offering.
🚚 Identify Customer-Specific Cost-to-Serve
Cost-to-serve is the set of costs created by the way a particular customer buys, receives, uses, and pays for a company’s offering. Two customers can buy the same product but generate very different cost-to-serve profiles.
Relevant costs may include order entry, small or frequent shipments, special packaging, returns handling, technical support, custom reports, account management time, collections work, and contract administration.
A large customer may deserve a lower unit price because of volume, but only if lower prices are not overwhelmed by the extra operational work required to support that relationship.
⏱️ Measure Time Where Services Drive Cost
In professional services, agencies, repair businesses, healthcare-adjacent practices, and many software implementation teams, labor time is often the largest delivery cost. If time is not captured reasonably well, profitability conclusions will be weak.
Time records do not need to become a surveillance exercise. Their purpose is to understand the economic effort involved in client work: planning, delivery, revisions, meetings, troubleshooting, administration, and rework.
Use a practical cost rate that reflects wages, benefits, payroll taxes, and, where appropriate, a sensible share of labor-related support costs. Billing rate alone is not a profit measure.
🏭 Trace Product Costs Beyond Materials
Product profitability is often understated or overstated because companies focus only on purchase price or raw material cost. Many products also use receiving, storage, picking, inspection, machine setup, warranty work, and return processing.
A low-volume customized product may require multiple setup changes and quality checks. A standardized high-volume product may move through the same facility with very little handling. Their production costs can differ sharply even if their material inputs are similar.
The goal is not to assign every possible cost immediately. It is to identify material differences in how products consume resources.
🧠 Understand Activity-Based Costing
Activity-based costing, often shortened to ABC, assigns costs based on the activities that cause them. Instead of spreading warehouse costs equally across all products, for example, a business might allocate relevant costs using order lines, picks, storage space, or shipments.
This approach is especially useful when indirect operating costs are significant and customer behavior varies widely. It can reveal that small, irregular orders cost more to process than large, predictable ones.
ABC is not automatically worth the effort for every organization. The system should remain proportionate to the decisions it is meant to improve.
⚙️ Choose Cost Drivers That Reflect Reality
A cost driver is a measurable factor that explains why a cost occurs. Good drivers have a logical relationship with the activity being measured.
| Activity | Possible cost driver | Why it may fit |
|---|---|---|
| Order processing | Number of orders or order lines | More orders generally create more entry and review work. |
| Shipping | Shipments, weight, or delivery distance | These factors may influence freight and handling effort. |
| Technical support | Support tickets or support hours | They connect cost to actual assistance provided. |
| Machine setup | Number of production runs | Setup work often occurs per run, not per unit. |
A driver is an approximation, not a physical law. Review it when operations change or when results appear inconsistent with what teams observe on the ground.
🛒 Do Not Let Discounts Hide in Plain Sight
Discounts are frequently treated as a sales tool rather than a cost decision. Yet every discount reduces revenue, often with a direct and immediate effect on margin.
Suppose a product has a 40% gross margin before discount. A substantial price reduction can eliminate much of the profit while leaving direct costs unchanged. The sales volume needed to recover the lost profit may be far larger than expected.
Track discounts by customer, product, salesperson, campaign, and reason code where feasible. This shows whether discounting is strategic, habitual, or compensating for a service problem.
↩️ Include Returns, Warranties, and Rework
Returns and warranty claims do more than reverse sales. They can create shipping, inspection, replacement, disposal, repair, customer service, and reputational costs.
Similarly, a service engagement with frequent revisions may appear profitable if only original project hours are considered. Once rework and unbilled corrections are included, the picture can change.
Where costs arise after the original sale, use historical patterns cautiously to estimate a reasonable expected cost. Flag assumptions clearly rather than presenting estimates as exact facts.
💳 Consider Payment Behavior and Working Capital
A profitable sale on paper can become less attractive when a customer pays consistently late, disputes invoices frequently, or requires unusually long credit terms. The company still needs cash to pay staff, suppliers, and operating expenses while waiting for collection.
For major accounts, review days outstanding, disputed balances, write-offs, and collection effort. Businesses that rely on borrowing may also consider the financing cost associated with slow-paying receivables.
This does not mean every late payer should be rejected. It means payment behavior belongs in a complete relationship assessment.
📦 Account for Inventory and Capacity Constraints
Not all profit is equally valuable when resources are limited. A product that produces a modest margin but consumes scarce machine hours, shelf space, or specialized labor may displace a more profitable alternative.
In these situations, examine contribution per constrained resource. If machine time is the bottleneck, compare contribution margin per machine hour. If skilled technicians are the constraint, compare contribution per technician hour.
This analysis helps managers decide what to prioritize when demand exceeds available capacity. It should not be used blindly if strategic commitments or long-term customer relationships are also at stake.
📈 Use Contribution Margin for Short-Term Decisions
Contribution margin is revenue minus variable costs: costs that change with the sale, such as materials, transaction fees, commissions, or incremental delivery costs. It shows how much a sale contributes toward fixed operating costs and profit.
Contribution margin is particularly useful for evaluating an additional order when facilities and staff are already in place. If the order creates positive contribution and does not displace better work, it may help cover fixed costs.
But it is not a complete long-term pricing model. Prices must eventually support the business’s ongoing fixed costs, investment needs, and desired return.
🧱 Treat Fixed Costs With Care
Fixed costs do not usually change immediately with one more sale. Examples include lease payments, salaried management, baseline software subscriptions, and certain insurance costs.
Allocating them to customers can be useful for evaluating full business economics, especially over a longer period. Yet a customer should not automatically be considered unprofitable merely because an arbitrary allocation exceeds its gross profit.
Ask a practical question: if this customer disappeared, which costs would actually disappear, decline, or be avoidable? That answer often gives a more decision-useful view than a broad allocation formula.
🗂️ Create a Customer Profitability Statement
A customer profitability statement organizes revenue and attributable costs in one place. It turns scattered operational data into a management tool.
A simple format can include:
- Net sales after discounts, rebates, and returns
- Direct product or service delivery costs
- Gross profit
- Customer-specific sales, support, logistics, and administration costs
- Contribution after cost-to-serve
- Optional allocated shared costs for long-term analysis
Keep the layers visible. Combining everything into one opaque “profit” number makes it hard to challenge assumptions or identify practical improvements.
🧩 Build an Equivalent View for Products and Services
Product and service profitability reports follow the same logic, but their cost categories differ. A product report may emphasize material cost, labor, setup, freight, returns, and warranty claims.
A service report may emphasize delivery hours, subcontractors, travel, software usage, project management, and rework. A subscription offering may require attention to onboarding, hosting, support tickets, and churn-related retention effort.
Use a consistent report structure across offerings, then add the specific drivers that matter to each business model.
🧪 Test the Results Against Operational Reality
Numbers should prompt conversations, not replace judgment. If a report says a supposedly valuable customer is barely profitable, ask account managers, operations teams, and finance staff what they see.
They may confirm the issue: repeated manual work, fragmented orders, difficult scheduling, or unusual support demands. Or they may uncover a data problem, such as costs coded to the wrong job or revenue assigned to the wrong product family.
This validation step helps distinguish a genuine economic insight from a reporting artifact.
🧹 Clean Data Before Seeking Precision
Profitability analysis depends on master data and transaction discipline. Customers must be consistently identified, products properly classified, and costs coded in a way that allows meaningful tracing.
Common problems include duplicate customer records, vague expense accounts, missing project codes, outdated product bills of materials, and sales recorded under broad categories that conceal pricing differences.
Start with the largest revenue streams and largest cost categories. A credible 80% view of the business is often more useful than a delayed system designed to capture every minor detail.
📅 Choose a Time Period That Tells the Truth
Monthly reports are useful for monitoring, but a single month can be misleading. An annual contract may require heavy onboarding early in the relationship, while revenue arrives evenly across the year.
Seasonal demand, project timing, large returns, renewal commissions, and infrequent warranty work can also distort short periods. Use a period long enough to capture the operating cycle being studied.
Compare multiple periods when possible. A customer’s profitability trend can be more informative than one isolated result.
🧭 Segment Before You Rank
Ranking every customer or product in one list can create poor comparisons. A national account with large volume and complex logistics may not be directly comparable to a local cash-and-carry customer. A custom engineering service should not necessarily be judged against a standardized maintenance plan.
Segment the analysis by meaningful characteristics, such as channel, geography, contract type, product family, customer size, or delivery model. Then compare similar relationships with similar cost structures.
Segmentation turns a blunt ranking into a more useful management conversation.
🚦Classify Profitability Into Action Groups
After measurement, classify customers, products, or services into practical groups. The purpose is not to label anyone “good” or “bad,” but to match each group with an appropriate action.
- High profit, high potential: protect service quality and look for sustainable growth.
- High revenue, low profit: investigate pricing, discounts, service demands, and process waste.
- Low revenue, high margin: assess whether targeted growth is realistic.
- Low profit, low strategic value: redesign, reprice, streamline, or consider exiting.
Strategic value can justify lower current profitability, but that rationale should be explicit and periodically reviewed.
💬 Discuss Price and Service Design Together
Low profitability does not always require a price increase. Sometimes the better answer is changing how the customer is served: minimum order sizes, standardized packaging, scheduled delivery days, paid expedited shipping, fewer custom reports, or a clearer support scope.
Pricing and service design work together. A customer may accept a higher price, a different service level, or a combination of both when the value exchange is explained clearly.
Before changing terms, identify the actual source of cost. Raising prices to solve an inefficient internal process may damage the relationship without fixing the underlying issue.
🤝 Recognize Strategic Value Without Hiding Losses
Some customers or offerings have benefits beyond immediate accounting profit. They may provide market credibility, learning opportunities, predictable volume, access to a new channel, or a relationship that supports other profitable work.
Those benefits can be real, but they should not become a vague excuse for indefinite losses. State the strategic rationale, estimate what can reasonably be assessed, assign an owner, and set a review date.
Separating strategic investment from routine operating performance gives leaders a clearer view of what they are choosing to fund.
⚠️ Avoid the Most Common Analysis Mistakes
Several errors repeatedly weaken profitability work:
- Ranking customers by sales alone.
- Ignoring discounts, returns, rebates, and credit notes.
- Using billed hours instead of actual delivery time on service work.
- Allocating all overhead with a single arbitrary percentage.
- Assuming historical costs will remain unchanged after a decision.
- Making decisions from one unusual month or one incomplete data extract.
- Treating estimated allocations as more precise than they are.
The remedy is not a perfect model. It is a transparent model with assumptions that managers can inspect, challenge, and improve.
🔁 Turn Reporting Into a Regular Management Cycle
A profitability report has limited value if it is produced once, discussed briefly, and forgotten. Build a recurring cycle: update data, review exceptions, investigate causes, decide actions, assign owners, and measure whether results change.
For example, if an account appears unprofitable because of frequent small deliveries, the action might be a revised delivery schedule. The follow-up question is whether shipment frequency and contribution improved after the change.
Regular review also catches drift. A once-profitable customer may become less attractive as discounts expand or service requirements increase.
🛠️ Start Small With a Practical First Model
You do not need a sophisticated enterprise system to begin. A spreadsheet, accounting data export, sales records, time data, and input from operations can produce an informative first model.
Choose a manageable scope: perhaps the top twenty customers, a single product family, or the service line with the greatest delivery effort. Trace direct costs, identify two or three meaningful cost-to-serve drivers, and document assumptions.
Then improve the model only where better data would change a real decision. Complexity is useful when it improves action, not when it merely makes a report look advanced.
🎯 Use Profitability Insights to Make Better Choices
The value of analysis lies in decisions. Profitability information can support pricing reviews, product rationalization, customer negotiations, sales compensation design, staffing plans, inventory decisions, and capital investment choices.
It can also improve fairness inside the organization. Sales teams gain clearer visibility into the economics behind discount approvals, while operations teams can show why certain customer requirements need different terms.
The most constructive use is not punishment. It is designing a business model in which customers receive real value and the company earns a sustainable return for providing it.
🏁 The Core Principle: Follow the Economics, Not the Sales Total
The customers, products, and services generating the most revenue are not always those generating the most profit. The difference is found by tracing direct costs, understanding cost-to-serve, considering capacity and payment behavior, and separating short-term contribution from long-term economics.
A useful profitability system is clear enough for managers to understand, grounded enough in operations to be credible, and flexible enough to improve as better information becomes available.
When reports connect revenue to the work, resources, and risks required to earn it, they become more than accounting schedules. They become a guide for choosing where the business should grow, redesign, negotiate, or stop.
The best profitability question is not “What sells the most?” but “What creates the most sustainable value after the full economic effort to serve it is understood?” 💰📊🧭