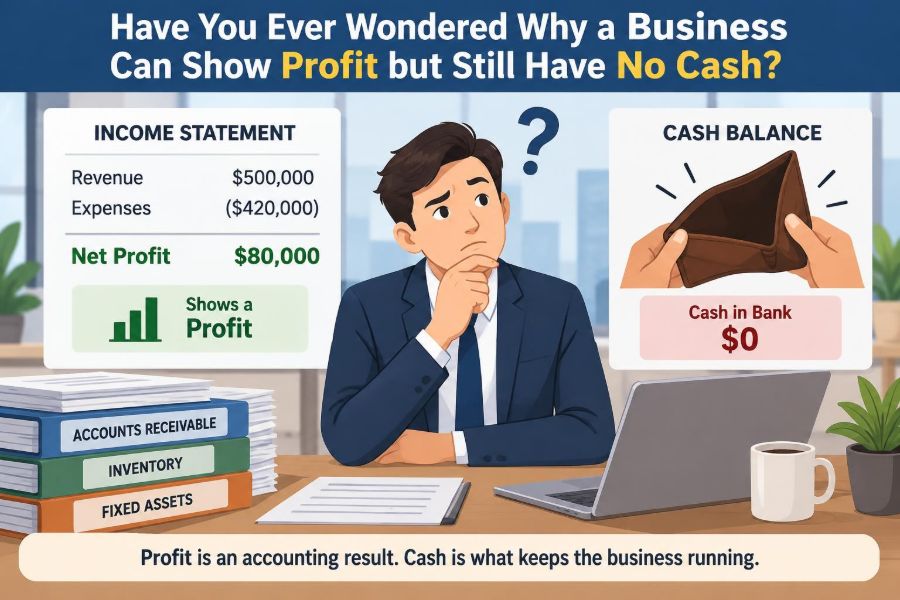

A business owner checks the income statement and sees a healthy profit. Sales are rising, expenses appear under control, and the business seems to be moving in the right direction.
Then payroll is due. A major supplier wants payment. The bank balance is far lower than expected, and the owner wonders how a profitable business can feel so financially strained.
This is not a contradiction. It is one of the most common and consequential distinctions in accounting: profit is not the same thing as cash.
Understanding that distinction helps students read financial statements correctly and helps managers avoid decisions based on a number that may look reassuring while cash pressure quietly builds.
🧭 Start With the Two Different Questions
Profit answers: Did the business earn more revenue than it incurred in expenses during a period? Cash answers: How much money is actually available to pay obligations right now?
Both matter, but they measure different things. A company can earn a profit on paper while waiting for customers to pay, while holding cash in inventory, or while repaying debt.
Think of profit as a measure of operating performance over time. Think of cash as the money that can be used immediately to meet commitments.
📄 What Profit Actually Measures
Profit, sometimes called net income or earnings, is calculated on the income statement. In basic form, it is revenue minus expenses for a reporting period.
If a business earns $100,000 in revenue and recognizes $80,000 in expenses, it reports $20,000 of profit. That result says the business created an accounting surplus during that period.
It does not automatically mean $20,000 was deposited into the bank. The revenue may not yet have been collected, and some expenses may not yet have been paid.
🏦 What Cash Represents
Cash includes currency, bank balances, and usually highly liquid cash equivalents. It is the resource used to pay employees, landlords, lenders, tax authorities, and suppliers.
A cash balance is a point-in-time measure, shown on the balance sheet. It reflects money received and money paid up to a specific date.
A company may have a large profit and a small cash balance at the same time. It may also have substantial cash after borrowing money even if it is currently unprofitable.
🧾 Why Accrual Accounting Creates the Difference
Most businesses prepare formal financial statements using accrual accounting. Under this approach, revenue is recognized when it is earned and expenses are recognized when they are incurred, rather than only when cash changes hands.
This matching approach gives a more useful picture of a period’s economic activity. A consulting firm that completes work in March should generally report March revenue even if the customer pays in April.
The trade-off is that income statement profit can include transactions that have not yet affected the bank account.
🔄 Cash Accounting Tells a Narrower Story
Under cash accounting, income is recorded when cash is received and expenses are recorded when cash is paid. This is often simpler for very small operations, but it can obscure what the business has earned or owes.
Suppose a retailer buys inventory in December but sells it in January. Cash accounting emphasizes the December payment and January receipt. Accrual accounting aims to connect the inventory cost with the January sale.
Neither method changes the total lifetime cash generated by the business. They differ mainly in the timing of recognition and the information they provide.
📬 Sales on Credit Can Create Profit Before Cash
The most familiar explanation is a credit sale. When a company delivers goods or services and invoices the customer, it may record revenue immediately even though payment is due later.
The unpaid amount becomes accounts receivable, an asset representing money customers owe. The sale can raise profit today while cash remains unchanged until the customer pays.
If collections are slow, the gap becomes financially dangerous. A business cannot use an invoice to make payroll unless it can collect it, borrow against it, or negotiate additional time to pay others.
⏳ A Simple Credit-Sale Example
Imagine a design agency completes a $30,000 project in June. Its direct costs and June operating expenses related to that work total $20,000. The agency records a $10,000 profit for June.
But the client’s invoice terms allow payment in 60 days. On June 30, the agency may have $30,000 in receivables but no new cash from that project.
If the agency paid its designers, software bills, and rent during June, its cash may actually have declined despite the reported profit.
🧱 Inventory Uses Cash Before It Produces Revenue
Inventory is another major reason profitable businesses face cash shortages. A manufacturer or retailer often pays for products, materials, freight, and storage long before making a sale.
Until inventory is sold, its cost is generally recorded as an asset, not immediately as an expense. The cash has left the business, but the income statement may not yet show the full effect.
When inventory eventually sells, its cost moves into cost of goods sold. That timing can make profit look sound while substantial cash is tied up on shelves or in warehouses.
🛒 Growth Can Make the Problem Worse
Fast growth sounds universally positive, but it can absorb cash at an alarming pace. More sales may require more inventory, more staff, more equipment, and larger unpaid customer balances.
For example, a wholesaler may need to purchase inventory months before customers pay for it. Every new order can increase reported revenue while also increasing the amount of cash required to keep operations moving.
This is why a growing company can fail from lack of liquidity even when its income statement shows increasing profits. Growth needs funding.
🤝 Accounts Payable Can Temporarily Preserve Cash
Accounts payable are amounts the company owes suppliers for goods or services already received. When a supplier offers payment terms, the company can use materials or services before paying cash.
Increasing payables can help conserve cash in the short term. If inventory arrives today but payment is due in 30 days, cash remains in the bank during that period.
However, delaying payments beyond agreed terms can damage supplier relationships, create late fees, interrupt deliveries, or signal financial distress. Payables are a timing tool, not a permanent solution.
📊 Working Capital Connects Daily Operations to Cash
Working capital is commonly calculated as current assets minus current liabilities. Current assets include items expected to turn into cash or be used within the operating cycle, such as cash, receivables, and inventory.
Current liabilities include obligations due relatively soon, including payables, wages payable, taxes payable, and short-term debt. The amount and quality of working capital influence a company’s ability to operate without disruption.
A positive working-capital figure is useful, but it is not a guarantee of safety. Inventory might be hard to sell, receivables may be overdue, or liabilities may come due before assets can become cash.
🚴 The Cash Conversion Cycle Explains the Timing
The cash conversion cycle tracks the time between paying for inventory or production inputs and collecting cash from customers. It links inventory days, collection days, and supplier payment days.
A shorter cycle generally means cash moves through operations more quickly. A longer cycle means the business must finance a longer period between spending and collection.
Businesses use different models. A custom builder may need deposits before beginning work, while a distributor may pay suppliers before selling goods and then wait again for customer payment.
🧮 Depreciation Lowers Profit Without Using Current Cash
Not every difference between profit and cash creates a cash shortage. Depreciation is an important example in the other direction.
When a business buys a long-lived asset such as machinery, it usually pays cash at purchase. Accounting then spreads the asset’s cost over its useful life through depreciation expense.
Depreciation reduces profit in later periods, but it does not require a new cash payment in those periods. This is one reason cash flow from operations can sometimes exceed net income.
🏗️ Capital Expenditure Is a Cash Outflow Outside Profit
Buying equipment, renovating a facility, or acquiring vehicles can consume large amounts of cash without immediately appearing as an expense on the income statement.
These purchases are usually treated as capital expenditures: cash spent to acquire or improve long-term assets. The expense is recognized gradually through depreciation or amortization rather than all at once.
A profitable restaurant, for instance, may have weak cash after opening a second location because construction, furniture, and kitchen equipment required upfront payment.
💳 Loan Repayments Affect Cash but Not Profit
Borrowing can put cash into the business, but repaying the principal portion of a loan takes cash out. Principal repayment is not an operating expense and therefore does not reduce profit.
Interest is different: interest expense generally reduces profit because it is the cost of borrowing. But the repayment of borrowed principal is a balance-sheet transaction.
A business may report a profit and still struggle because it faces large scheduled principal payments. The income statement alone will not reveal the full pressure.
🧾 Taxes Can Arrive on a Different Schedule
Tax expense recognized in financial statements and taxes paid in cash may not occur in exactly the same period. Timing differences can arise from payment schedules, estimated payments, deductions, credits, and the rules applicable to a particular business.
The practical issue is straightforward: managers need to plan for tax cash payments even when the accounting expense was recognized earlier or later.
Tax treatment varies by jurisdiction and entity type, so businesses should obtain advice tailored to their circumstances rather than assuming a general accounting example determines their tax obligation.
🎁 Prepayments Move Cash Before Expense
A company may pay insurance, rent, software subscriptions, or service contracts in advance. At payment, cash declines, but the amount may first be recorded as a prepaid asset.
The expense is recognized as the benefit is consumed. An annual insurance payment made in January may reduce cash immediately while the expense is allocated across the coverage period.
This is another reminder that an expense is not always a current-period cash payment, and a current-period cash payment is not always an expense.
📉 Losses Can Also Exist Alongside Strong Cash
The reverse situation is possible. A company can report a loss while holding plenty of cash, especially after receiving a loan, investor funding, an owner contribution, or advance customer deposits.
It might also record a non-cash expense such as depreciation that lowers accounting profit without reducing cash in the same period.
Strong cash does not automatically mean a business model is sustainable. It may simply mean outside financing or prior cash reserves are currently covering operating losses.
📚 The Three Financial Statements Tell the Full Story
No single financial statement answers every financial question. The income statement explains performance over a period, the balance sheet shows financial position on a date, and the cash flow statement explains changes in cash.
| Statement | Primary question | Useful warning sign |
|---|---|---|
| Income statement | Did operations generate profit? | Profit depends heavily on uncollected sales |
| Balance sheet | What does the business own and owe? | Receivables or inventory are growing rapidly |
| Cash flow statement | Where did cash come from and go? | Operations consistently consume cash |
Reading these statements together prevents a common mistake: treating net income as though it were a bank balance.
🌊 Operating Cash Flow Is Especially Revealing
Cash flow from operating activities focuses on cash generated or used by ordinary business operations. It begins with net income under the indirect method and adjusts for non-cash items and changes in working-capital accounts.
If receivables increase, operating cash flow is reduced because revenue was recorded without collection. If inventory increases, operating cash flow is reduced because cash was used to build stock.
A single period of lower operating cash flow may be normal, particularly during planned expansion. A persistent mismatch deserves careful investigation.
🔍 Read the Reconciliation, Not Just the Bottom Line
Under the indirect cash flow statement format, the reconciliation from net income to operating cash flow explains why profit and cash differ. It is often one of the most informative parts of the financial statements.
Look for large movements in receivables, inventory, prepayments, payables, and accrued liabilities. Then ask what operational event caused each movement.
A rise in receivables could reflect healthy sales growth, weak collections, one unusually large invoice, or a customer facing financial difficulty. The number needs context.
🚩 Warning Signs Behind a Profitable Result
Profitability should prompt further questions when cash does not follow. Certain patterns can indicate that a company’s reported earnings are not yet translating into usable liquidity.
- Receivables rise faster than sales, particularly if invoices are overdue.
- Inventory grows without a clear sales forecast or seasonal reason.
- Supplier payments are routinely delayed to preserve bank balances.
- Short-term borrowing is repeatedly needed to fund normal operations.
- Operating cash flow remains weak while profit continues to rise.
- A few customers account for a large share of unpaid invoices.
None of these signs proves failure or misconduct. They are signals to examine the operating cycle, financing arrangements, and assumptions behind the plan.
🧠 Profit Quality Matters
Profit quality refers broadly to how sustainable, understandable, and cash-supported reported earnings appear. Revenue from customers who reliably pay is generally more useful than revenue associated with uncertain collection.
Recurring sales, reasonable credit terms, stable margins, and disciplined expense recognition can support stronger-quality earnings. By contrast, one-off transactions, aggressive assumptions, or large unexplained working-capital changes require more scrutiny.
This is not about dismissing accrual accounting. It is about checking whether accounting profit is likely to become cash on a reasonable timetable.
📝 Better Invoicing Accelerates Collection
For many service businesses, cash flow improves through basic billing discipline. Send invoices promptly, make payment terms clear, confirm the correct customer contact, and resolve disputes before invoices become overdue.
Milestone billing can be useful for lengthy projects. Rather than financing months of work until final delivery, a business may invoice when defined stages are completed.
Deposits and retainers can also reduce upfront cash strain when appropriate for the industry and agreed clearly with customers. The goal is not merely to collect faster; it is to align payment timing with the cost of doing the work.
📦 Manage Inventory With Cash in Mind
Inventory decisions are not only merchandising or production decisions. They are financing decisions because each unit held represents cash that cannot be used elsewhere.
Businesses can improve visibility by monitoring slow-moving items, obsolete stock, supplier lead times, forecast accuracy, and reorder practices. The right inventory level balances stockout risk against the cost of tying up capital.
Cutting inventory too aggressively can lose sales or disrupt production. Carrying too much can create storage costs, markdowns, deterioration, and a cash squeeze.
🤝 Negotiate Terms Without Damaging Relationships
Customer and supplier terms shape the cash conversion cycle. A business may seek earlier customer payments, deposits, progress payments, or electronic payment options while negotiating supplier terms that reflect its actual selling cycle.
Good negotiations are transparent and commercially realistic. A supplier may support extended terms for a reliable customer with a clear payment history, but chronic late payment is different from an agreed extension.
Cash management works best when it protects the relationships that make operations possible.
🗓️ Build a Rolling Cash Forecast
A budget estimates expected performance. A cash forecast estimates when money is expected to enter and leave the bank account.
A rolling forecast should list expected customer collections, payroll dates, rent, taxes, supplier payments, debt service, capital spending, and other material commitments. Update it regularly as actual timing changes.
Forecasts are estimates, not promises. Their value comes from exposing future shortfalls early enough to collect receivables, delay discretionary spending, arrange financing, or renegotiate timing.
🔐 Keep a Liquidity Buffer
A liquidity buffer is cash or reliable unused funding capacity reserved for normal uncertainty: a late-paying customer, a seasonal dip, an equipment repair, or a temporary rise in costs.
The appropriate buffer differs by industry, volatility, fixed obligations, access to credit, and customer concentration. A business with predictable subscriptions faces different risks from one dependent on a few large project invoices.
Borrowing can bridge temporary timing gaps, but debt adds repayment and interest obligations. It should support a credible cash plan rather than hide a structurally cash-consuming operation.
🧑💼 Owners Must Separate Business Cash From Personal Cash
In small businesses, owners may see a profitable month and withdraw money without considering upcoming obligations. An owner draw or distribution reduces business cash even though it is not always an operating expense.
That can leave insufficient funds for taxes, payroll, inventory, or loan payments. The accounting result may remain profitable while the operating account becomes fragile.
Clear policies for owner compensation, distributions, and retained cash help prevent personal withdrawals from disrupting business commitments.
⚖️ Do Not “Fix” Cash Problems With Accounting Entries
Changing a journal entry does not create cash. Proper accounting may clarify when revenue or expenses belong, but it cannot solve slow collections, overstocked inventory, excessive debt payments, or unplanned capital spending.
Misstating revenue, delaying valid expenses, or recording unsupported assets may make a report look better temporarily, but it weakens decisions and can create serious reporting, legal, and ethical consequences.
The right response is operational and financial: understand the timing gap, correct the cause where possible, and finance it appropriately when necessary.
🧭 A Practical Monthly Review Routine
A regular review turns this concept into a management habit. Compare profit, operating cash flow, and the closing bank balance, then investigate meaningful differences.
- Review the aging of receivables and identify specific collection actions.
- Compare inventory levels with demand, orders, and expected turnover.
- List payments due over the coming weeks, including tax and debt obligations.
- Update the rolling cash forecast using realistic collection dates.
- Separate one-time cash uses from recurring operating needs.
- Decide early whether the answer is collection, cost control, new terms, or financing.
This routine is useful even for profitable companies because it protects the ability to continue operating while profits are still being converted into cash.
🎯 The Core Principle: Earnings Must Eventually Become Cash
Profit remains essential. Over the long run, a business normally needs a viable model that earns more than it consumes. But short-term survival depends on having enough cash at the right time.
Receivables, inventory, prepayments, debt principal, capital expenditures, and tax timing can all separate reported profit from available cash. The cash flow statement and forecast reveal whether that gap is manageable.
The key question is not simply, “Are we profitable?” It is also, “When will this profit turn into cash, and can we meet every obligation before then?”
A business can be profitable on paper and still run out of cash because accounting profit measures performance, while cash flow measures the timing and availability of money. Read both, manage the gap, and treat liquidity as an operating priority—not an afterthought. 💰📊