
A manager is deciding whether to approve a large customer’s request for longer payment terms. A lender is reviewing a loan application from a growing manufacturer. An investor is comparing two retailers that both appear profitable on the surface.
Each person faces the same problem: financial statements contain plenty of numbers, but raw numbers alone do not reveal whether a business is liquid, efficient, heavily indebted, or sustainably profitable.
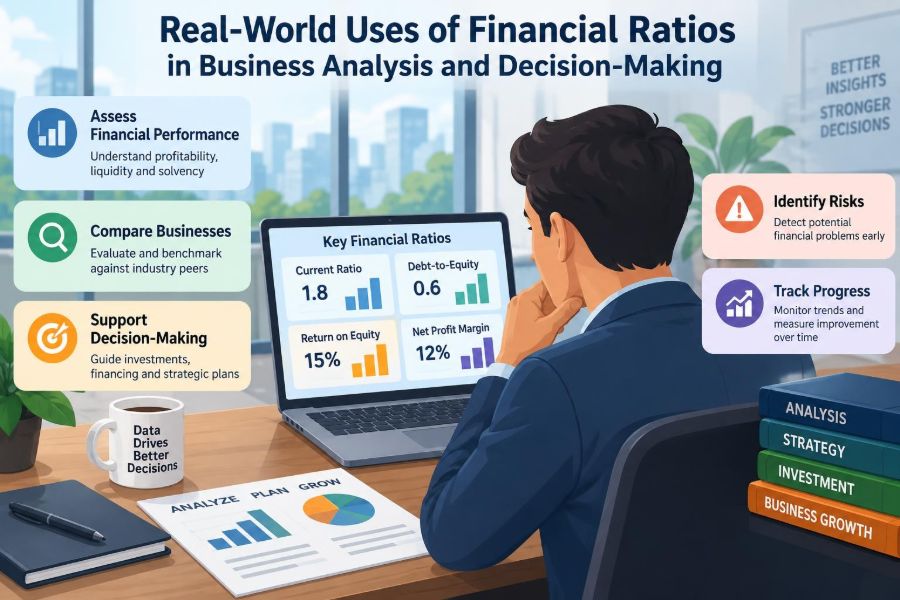
Financial ratios turn accounting data into relationships that can be compared across periods, competitors, and business models. They help convert a balance sheet, income statement, or cash flow statement into questions that support decisions.
Used well, ratios guide investigation rather than replace judgment. They reveal where to look, what to ask, and whether the story a business tells is consistent with its financial position.
🧭 What Financial Ratios Actually Do
A financial ratio divides or compares two related accounting figures. For example, the current ratio compares current assets with current liabilities, while gross margin compares gross profit with sales.
The resulting number provides context. Cash of $500,000 may sound strong or weak depending on upcoming obligations; comparing available short-term resources with short-term debts makes the number meaningful.
Ratios are analytical tools, not scores. A “good” level depends on the industry, the company’s strategy, its operating cycle, and the quality of the underlying accounting data.
📚 The Statements Behind the Ratios
Most ratios begin with three core statements. The balance sheet shows assets, liabilities, and equity at a date. The income statement reports revenue, expenses, and profit over a period. The cash flow statement explains movements in cash.
Liquidity and leverage measures rely heavily on the balance sheet. Profitability measures usually combine income statement figures with balance sheet amounts. Efficiency measures often connect a period’s sales or cost of sales to an average asset balance.
Before calculating anything, confirm that figures cover comparable periods and use consistent accounting policies. A ratio built from mismatched dates can create a misleading conclusion.
🔎 Start With the Decision, Not the Formula
The most useful ratio is the one that addresses a real decision. A purchasing manager deciding whether to extend credit needs evidence about a customer’s ability and habit of paying. An owner considering new equipment needs evidence about borrowing capacity, cash generation, and asset use.
Useful starting questions include:
- Can the business meet obligations coming due soon?
- Is profit being converted into operating cash?
- Is growth funded by operations, debt, or owner capital?
- Are inventory, receivables, and fixed assets being used productively?
- Has financial risk increased faster than the business’s ability to service it?
Choosing the question first prevents the common habit of calculating every available ratio without a purpose.
💧 Current Ratio and Short-Term Solvency
The current ratio is current assets divided by current liabilities. It estimates whether assets expected to be used or converted to cash within roughly one year can cover obligations due in a similar period.
A ratio of 1.5 means the company reports $1.50 of current assets for every $1.00 of current liabilities. That can provide a cushion, but its reliability depends on what the current assets contain.
A retailer with rapidly selling inventory may operate comfortably with a lower current ratio than a contractor whose receivables take months to collect. The ratio is a first screening tool, not proof of liquidity.
⚡ Quick Ratio and the Quality of Current Assets
The quick ratio, often called the acid-test ratio, removes inventory and usually prepaid expenses from current assets before dividing by current liabilities. It focuses on cash, marketable investments, and receivables that may be converted to cash more quickly.
This distinction matters when inventory could be slow-moving, specialized, obsolete, or difficult to sell without price reductions. A company can show a comfortable current ratio while holding cash tied up in goods customers do not want.
For a distributor, the gap between the current and quick ratios is a useful prompt: how much of apparent liquidity depends on inventory being sold as expected?
🏦 Cash Ratio and Immediate Payment Capacity
The cash ratio uses only cash, cash equivalents, and sometimes highly liquid short-term investments, divided by current liabilities. It shows capacity to cover obligations immediately without collecting receivables or selling inventory.
It is deliberately conservative. Many healthy businesses do not maintain enough cash to pay every current liability at once because invoices are not all due on the same day.
Still, a sharp decline can matter when a business has volatile sales, a large debt payment approaching, or limited access to financing. Pair it with a cash flow forecast before reaching conclusions.
🧾 Receivables Turnover and Credit Control
Accounts receivable turnover generally divides credit sales by average accounts receivable. It indicates how often, during the period, the business collects its average receivables balance.
A higher turnover may signal timely collection, although it could also reflect very strict credit terms that discourage valuable customers. A lower figure may result from generous terms, disputed invoices, weak collection procedures, or a deliberate move into enterprise sales.
For example, if sales rise but receivables rise much faster, management should ask whether revenue growth is being financed by the company’s own cash.
📅 Days Sales Outstanding and Collection Timing
Days sales outstanding, or DSO, translates receivables into an estimated collection period. A common calculation is average accounts receivable divided by credit sales, multiplied by the number of days in the period.
Managers often find days easier to discuss than turnover. If stated payment terms are 30 days but DSO steadily moves toward 50 days, the issue may be invoice accuracy, customer credit quality, unaddressed disputes, or insufficient follow-up.
DSO works best alongside an accounts receivable aging report. An average can conceal a small group of seriously overdue balances.
📦 Inventory Turnover and Stock Discipline
Inventory turnover commonly divides cost of goods sold by average inventory. It estimates how often inventory is sold and replenished during a period.
Fast turnover can reduce storage costs, damage, and obsolescence. But a rate that is too high may mean frequent stockouts, rushed purchasing, or lost sales. Slow turnover can be acceptable for seasonal goods, long production cycles, or businesses that intentionally offer wide selection.
The practical question is whether inventory levels match demand, lead times, service expectations, and the company’s cash capacity.
⏳ Days Inventory Outstanding and Working Capital
Days inventory outstanding converts inventory turnover into an estimated number of days items remain in stock. It helps operational teams connect accounting data with buying, production, warehousing, and sales decisions.
Imagine a hypothetical electronics seller whose days inventory outstanding rises while product margins fall. The combination may suggest aging products that will require discounts, which can affect both cash flow and future profitability.
Break the analysis down by product category when possible. Aggregate inventory ratios can hide fast-moving staples behind a small amount of stagnant inventory.
🚚 Payables Turnover and Supplier Relationships
Accounts payable turnover compares purchases, or a suitable cost proxy, with average trade payables. It indicates how quickly a company pays suppliers. Days payable outstanding expresses the same pattern in days.
Paying suppliers more slowly preserves cash in the short term, but it can lead to missed early-payment discounts, damaged relationships, supply interruptions, or loss of favorable terms. Paying unusually quickly can also strain cash unnecessarily.
Interpret payment timing against agreed terms and industry practice. A change in the ratio is often more informative than one isolated number.
🔄 The Cash Conversion Cycle
The cash conversion cycle brings working-capital ratios together: days inventory outstanding plus DSO minus days payable outstanding. It approximates how long cash is committed between paying for inventory and collecting from customers.
A shorter cycle generally frees cash for payroll, debt reduction, expansion, or distributions. A longer cycle is not automatically poor; businesses with custom manufacturing or seasonal inventory can require more time.
Operational decisions can improve the cycle: better demand forecasting, faster invoicing, disciplined collection, and supplier terms aligned with the business’s own customer terms.
🏭 Total Asset Turnover and Productive Capacity
Total asset turnover divides revenue by average total assets. It shows how much sales a company generates from its asset base.
Asset-light service firms often have higher asset turnover than manufacturers that require plants, machinery, and inventory. Comparing them directly would say little about management quality because their economics differ.
Within the same industry, falling asset turnover can signal unused capacity, weak sales, excessive investment, or acquisitions that have not yet produced expected revenue. It should be examined with profit margins, not alone.
🏪 Fixed Asset Turnover and Capital Investment
Fixed asset turnover compares sales with average property, plant, and equipment. It is especially relevant for manufacturers, utilities, transport businesses, and other organizations that depend on long-lived operating assets.
A new factory or fleet can reduce the ratio initially because the asset enters the balance sheet before its full revenue contribution appears. That is not necessarily a failure; it may reflect planned expansion.
Decision-makers should ask whether utilization is improving over time and whether maintenance, depreciation, and financing costs remain sustainable.
📈 Gross Margin and Pricing Power
Gross margin is gross profit divided by revenue. It reveals the share of each sales dollar remaining after direct costs of goods sold or services delivered, before operating expenses, interest, and taxes.
A declining gross margin can result from price discounts, higher input costs, unfavorable product mix, waste, freight costs, or accounting classification changes. Sales growth does not compensate automatically if each sale generates less contribution toward overhead.
Review margin by product line, customer group, channel, or geography when data permits. A blended average can conceal where performance is changing.
🛠️ Operating Margin and Core Business Performance
Operating margin divides operating income by revenue. It extends the gross-margin view by incorporating operating costs such as selling, administration, and research or development, while excluding financing and tax effects.
This makes it useful when comparing businesses with different debt structures. A company can have sound operations but low net income because interest expense is heavy; operating margin helps separate the operating engine from financing choices.
A rising operating margin may result from scale, cost control, or better pricing. It can also reflect temporary expense cuts, so assess whether the improvement can continue without damaging operations.
🎯 Net Profit Margin and the Bottom Line
Net profit margin divides net income by revenue. It shows the final portion of sales retained after operating expenses, interest, taxes, and other reported items.
It is a familiar measure but can be influenced by unusual gains or losses, tax changes, asset sales, and financing decisions. A single year’s net margin should not be treated as a stable earnings rate without checking the notes and income statement details.
For owners, net margin connects sales strategy with ultimate return. For analysts, it is most useful alongside gross and operating margins that explain where the result was created.
🧮 Return on Assets and Resource Efficiency
Return on assets, or ROA, generally divides net income by average total assets. It estimates the profit generated from resources controlled by the business.
ROA is useful when management is deciding whether new assets are earning enough to justify their cost. Yet accounting depreciation methods, acquired intangible assets, and asset revaluations can affect comparability.
An asset-intensive company may have lower ROA than a software firm even when both are well run. Use industry-relevant comparisons and consider operating return measures where financing differences are significant.
👥 Return on Equity and Shareholder Returns
Return on equity, or ROE, divides net income by average shareholders’ equity. It describes the return earned on owners’ recorded investment.
A high ROE can reflect strong profitability and efficient capital use. It can also be boosted by high borrowing, share repurchases, or a small equity base after prior losses. For that reason, high ROE should lead to a leverage review rather than immediate celebration.
For closely held businesses, ROE can help owners compare the return from retaining money in the company with alternative uses of capital, while recognizing that personal compensation policies affect reported profit.
🧩 DuPont Analysis and the Drivers of ROE
DuPont analysis breaks ROE into three components: net profit margin, total asset turnover, and financial leverage. The framework explains whether return on equity is being driven by profitability, efficient asset use, or greater reliance on debt.
| Driver | What a change may indicate | Question to ask |
|---|---|---|
| Net profit margin | Pricing, costs, or non-operating effects | Is earnings quality improving? |
| Asset turnover | Sales generated from assets | Are assets fully utilized? |
| Financial leverage | Use of debt relative to equity | Can obligations be serviced safely? |
This decomposition prevents a simplistic interpretation of ROE. Two companies may report the same ROE for fundamentally different, and differently risky, reasons.
⚖️ Debt-to-Equity and Capital Structure
The debt-to-equity ratio compares borrowed funds with owners’ equity. It provides a view of how the business finances its assets and how much of the capital structure depends on creditors.
Debt can support expansion, preserve ownership, and match long-lived assets with long-term funding. It also introduces required interest and principal payments, which can become difficult during a downturn or cash-flow disruption.
Assess debt maturity, interest-rate exposure, loan covenants, and the predictability of operating cash flow. The same ratio carries different risk in a stable subscription business and a cyclical construction company.
🛡️ Interest Coverage and Debt-Servicing Capacity
Interest coverage commonly divides earnings before interest and taxes by interest expense. It asks a direct question: how much operating profit is available to meet interest costs?
A stronger coverage figure usually provides more room for earnings volatility. But operating profit is not cash, and coverage does not include principal repayments, capital expenditure needs, or lease commitments.
When reviewing a borrower, lenders and managers should also inspect cash flow from operations and forecast periods when debt payments peak.
💵 Operating Cash Flow Ratios and Cash Reality
Profit is calculated under accrual accounting, meaning revenue and expenses are recognized when earned or incurred rather than strictly when cash moves. Cash flow ratios help test whether earnings are supported by cash collection.
One useful measure divides operating cash flow by current liabilities. Another compares operating cash flow with capital expenditures, debt obligations, or net income, depending on the decision.
If profit rises while operating cash flow weakens, investigate working capital, revenue recognition, customer collections, and one-off timing effects. The pattern is a signal to investigate, not an automatic finding of poor reporting.
🧪 Trend Analysis Makes Ratios More Useful
A ratio becomes more informative when viewed across several reporting periods. A current ratio of 1.4 has limited meaning alone; a steady fall from 2.0 to 1.4 while short-term borrowing grows tells a more useful story.
Use a simple trend sheet that records each ratio, the numerator and denominator, major business events, and management explanations. This creates an audit trail for assumptions and prevents an analyst from reacting to a temporary fluctuation.
Seasonal businesses require care. Comparing a holiday retailer’s year-end inventory with a quieter quarter may create distorted conclusions unless the same points in the operating cycle are compared.
🏷️ Benchmarking Against the Right Peers
External comparisons can reveal whether a result is unusual, but the peer group must be economically similar. Match businesses by industry, size, geography where relevant, customer model, and stage of development.
A premium retailer may intentionally carry more inventory and earn a higher margin than a discount retailer. Neither ratio profile is automatically superior because each reflects a different value proposition.
Published industry averages can also hide wide variation. Use them as reference points, then return to company-specific evidence, strategy, and historical performance.
🧾 Accounting Policies Can Change the Picture
Ratios inherit the limitations of accounting measurements. Inventory costing methods, depreciation estimates, impairment charges, revenue recognition judgments, lease accounting, and capitalization policies can alter both numerators and denominators.
For example, capitalizing a cost rather than expensing it immediately may increase current profit and assets, affecting margins, ROA, and turnover. That does not automatically mean the accounting is wrong, but comparisons should account for the policy choice.
Read the notes to financial statements when a ratio shifts sharply or when comparing companies with different reporting practices.
🚩 Red Flags Ratios Can Help Surface
Ratios do not detect every problem, but certain combinations deserve attention. The goal is not to accuse a business; it is to identify questions requiring evidence.
- Revenue increasing while receivable days lengthen substantially.
- Inventory days rising while gross margin declines.
- Net income growing without comparable operating cash flow.
- ROE increasing mainly because equity has fallen and debt has risen.
- Interest coverage weakening as borrowing expands.
- Current liquidity appearing strong only because inventory has accumulated.
Follow each warning sign to transaction-level information, management explanations, budgets, contracts, and cash forecasts.
🧠 Common Interpretation Mistakes
The first mistake is treating one ratio as a verdict. The second is assuming that higher is always better. The third is comparing organizations with different business models as though their ratios should match.
Other frequent errors include using ending balances instead of average balances where a period measure is appropriate, mixing annual income-statement amounts with interim balance-sheet figures, and overlooking non-recurring events.
Strong analysis states the limitation directly: “This ratio suggests slower collection, but seasonality and a recent billing-system change should be examined before drawing a conclusion.”
🗂️ Building a Practical Ratio Review
A repeatable process makes ratio analysis useful in meetings, lending reviews, and planning cycles. Start small with measures tied to the business’s main risks rather than creating a crowded dashboard.
- Define the decision and the audience.
- Select a balanced set of liquidity, efficiency, profitability, leverage, and cash flow ratios.
- Use consistent source data and document calculations.
- Compare trends, plans, and appropriate peers.
- Investigate material movements with operational evidence.
- Assign actions, owners, and review dates.
A ratio report is valuable only when it changes a decision, triggers a useful question, or confirms that a key risk remains controlled.
🤝 Using Ratios in Different Business Decisions
Credit teams may prioritize DSO, operating cash flow, current liquidity, and debt service capacity before changing customer terms. Operations leaders may focus on inventory days, gross margin, and fixed asset utilization.
Investors often connect margins, ROA, ROE, leverage, and free cash generation to assess the durability of returns. Owners considering expansion may examine turnover, interest coverage, projected liquidity, and the cash conversion cycle together.
The same formula can serve different users, but its interpretation must fit the decision. Financial analysis becomes stronger when finance, sales, operations, and leadership discuss the drivers behind the numbers together.
✅ The Core Principle: Ratios Start Better Questions
Financial ratios work best as a connected system. Liquidity explains near-term pressure, efficiency explains how resources move, profitability explains earnings power, leverage explains financing risk, and cash flow tests whether reported performance is being realized in cash.
Use ratios to compare like with like, track meaningful change, and investigate the business activity behind the calculation. Do not use them to substitute a neat number for informed judgment.
The real value of financial ratios is not the formula itself; it is the better decision made after understanding what the formula reveals and what it leaves unanswered. 💰📊