
A profitable month can still feel stressful when the bank balance is low. A customer may pay two weeks late, payroll may fall before a large invoice is collected, or an annual insurance bill may arrive just when inventory needs replenishing.
These moments do not always mean the business is failing. Often, they reveal a timing problem: cash is arriving and leaving on a different schedule than the owner expected.
A monthly cash-flow forecast makes that schedule visible before it becomes a crisis. It turns planned sales, bills, debt payments, taxes, and owner decisions into a practical view of the cash likely to be available.
For a small business, this is less about predicting the future perfectly than creating an early-warning system. With a reliable process, decisions about spending, borrowing, hiring, and growth become calmer and better timed.
🧭 Understand What a Cash-Flow Forecast Actually Does
A cash-flow forecast estimates the money expected to move into and out of a business over a future period. A monthly forecast groups those movements by month and calculates the expected closing cash balance at the end of each month.
Its central question is straightforward: will the business have enough available cash to meet its obligations when they fall due? That is different from asking whether the business is profitable over the same period.
A forecast is a management tool, not a promise. Actual customer payments, sales, and costs will vary. Its value comes from making assumptions explicit, testing them, and updating the plan as new information arrives.
🔄 Separate Cash Flow From Profit
Profit is generally revenue minus expenses for an accounting period. Cash flow tracks when money actually enters or leaves the bank account.
Suppose a consulting business completes a $10,000 project in March and sends an invoice that will be paid in May. The March income statement may show revenue and profit, but the cash does not support March payroll or rent.
The reverse can happen with expenses. Buying a year of insurance may require a large cash payment today, even though accounting records the cost across multiple months. A cash forecast must follow the payment date, not only the accounting treatment.
🏦 Start With the Real Opening Cash Balance
Every forecast begins with the actual cash available at the start of the first month. Use reconciled bank balances where possible, rather than an estimate based on memory or an old accounting report.
Include accessible operating cash and, if useful for planning, separate savings or reserve accounts. Do not treat unused credit on a credit card or line of credit as cash; it is borrowing capacity, not money already owned.
If funds are restricted for payroll taxes, customer deposits, or a specific purpose, identify them separately. A healthy-looking balance can be misleading when part of it cannot responsibly be spent.
📅 Choose a Forecast Horizon That Supports Decisions
A rolling 12-month forecast is often useful for small businesses because it captures seasonal patterns, annual renewals, loan obligations, and expected growth plans. “Rolling” means adding a new month whenever one month ends.
A three-month view may be enough for a very stable business with few major commitments. A business facing uneven sales, tight cash, expansion, or significant project work may benefit from looking 12 to 18 months ahead.
Monthly columns are a practical starting point. When cash is especially tight, add a short-term weekly cash forecast for the next four to 13 weeks. Monthly forecasts reveal the direction; weekly forecasts help manage exact payment timing.
🗂️ Build a Simple Forecast Layout
A spreadsheet is enough for many businesses. Accounting software, forecasting tools, and bank-connected apps can speed up data collection, but the underlying structure remains the same.
| Forecast line | What it represents | Example |
|---|---|---|
| Opening cash | Cash available at the month’s start | Reconciled bank balance |
| Cash receipts | Money expected to arrive | Customer payments, cash sales, loan proceeds |
| Cash disbursements | Money expected to leave | Payroll, rent, suppliers, tax payments |
| Net cash flow | Receipts less disbursements | Monthly increase or decrease |
| Closing cash | Expected ending balance | Opening cash plus net cash flow |
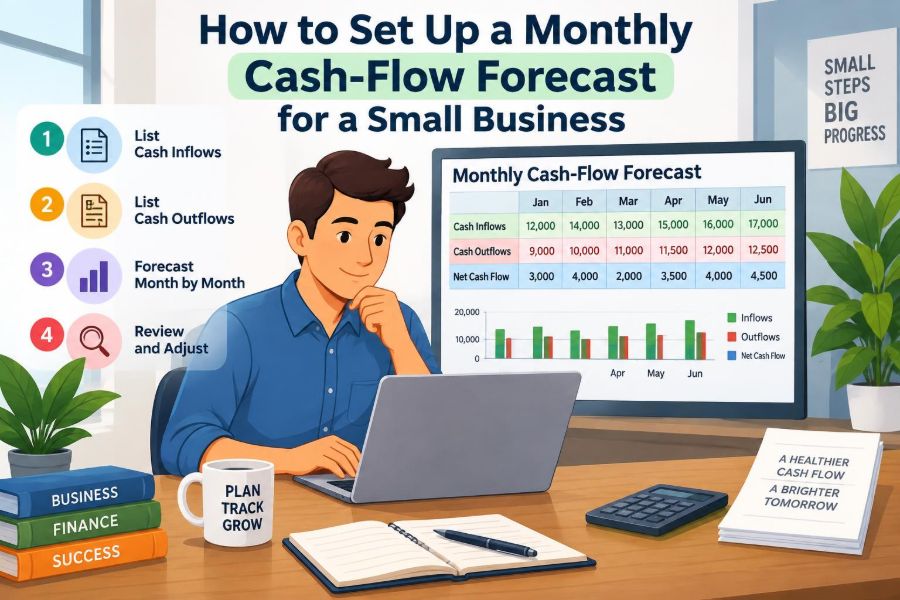
The fundamental calculation is: closing cash = opening cash + total cash inflows − total cash outflows. The closing cash for one month becomes the opening cash for the next.
🧾 Gather Source Data Before Making Assumptions
A good forecast is built from evidence already available in the business. Start by collecting recent bank statements, accounting reports, open customer invoices, unpaid supplier bills, payroll schedules, debt statements, lease agreements, and tax payment dates.
Reviewing several prior months helps reveal normal payment patterns. For example, a customer with 30-day terms may routinely pay 45 days after invoicing. Forecasting their contractual due date rather than their actual habit can overstate near-term cash.
For a newer business without much history, use contracts, supplier quotes, written payment terms, and conservative assumptions. Label uncertain entries so they can be revisited easily.
💵 Forecast Cash Sales by Collection Date
Cash sales include payments received at the time of purchase through cash, card processors, online payment platforms, or immediate bank transfer. Forecast these receipts in the month the money is expected to reach the bank.
Card transactions create a common timing issue. A sale made on the final day of the month might be deposited after the month closes, depending on processor settlement timing. The sales report and bank deposit date may not match.
Use recent daily or weekly sales patterns for a sensible monthly estimate. If the business has clear seasonality, compare the same period in prior years rather than relying only on the immediately preceding month.
📨 Forecast Invoice Collections, Not Just Invoices Sent
For credit sales, the critical forecast item is customer collection. An invoice is not a cash receipt until the customer pays it.
Create a schedule of open invoices with invoice date, due date, amount, and expected collection date. Consider known facts: an approved payment run, a disputed item, a customer who pays in installments, or an invoice still awaiting purchase-order approval.
It can help to categorize receivables by confidence:
- High confidence: payment is scheduled or historically reliable.
- Moderate confidence: due within terms but not confirmed.
- Low confidence: disputed, overdue, or dependent on uncertain customer activity.
Do not use low-confidence collections to justify essential spending without a backup plan.
🧮 Account for Other Sources of Cash
Customer payments are not the only inflows. Other possible sources include interest received, asset sales, owner contributions, tax refunds, grants, insurance proceeds, or loan drawdowns.
List these separately from operating sales. A loan drawdown can solve a short-term gap, but it does not indicate that day-to-day operations are generating enough cash. Keeping it visible prevents financing from being mistaken for revenue.
Only include uncertain funds when there is a reasonable basis for expecting them. A financing application or a hoped-for investment should not be treated as available cash until terms and timing are sufficiently clear.
🏢 List Fixed Operating Payments First
Fixed or relatively predictable costs provide the backbone of the outflow side of the forecast. Typical examples include rent, base utilities, software subscriptions, insurance installments, recurring professional fees, and equipment leases.
Use the actual payment date rather than dividing every cost evenly across the year. An annual subscription paid in January may create a January cash dip even if accounting expense is recognized monthly.
Checking direct debits and automatic card payments is essential. These costs are easy to forget precisely because they happen without a fresh invoice approval each month.
👥 Put Payroll and People Costs on the Correct Dates
Payroll is often one of the largest and least flexible cash outflows. Forecast gross wages, employer payroll-related costs where applicable, benefits, reimbursements, contractor payments, commissions, and bonuses on their actual payment schedules.
Businesses with biweekly pay may have months containing three paydays. If a forecast simply uses one-twelfth of annual payroll every month, it can miss this predictable cash pressure.
Include planned hires, wage changes, seasonal staff, and expected overtime. But distinguish approved decisions from possibilities: a position under consideration should be marked as a scenario, not quietly included as a certainty.
📦 Match Inventory and Supplier Payments to Terms
Inventory businesses must forecast both the purchase and the supplier payment. Stock may be ordered in one month, received in another, and paid later under credit terms.
For example, a retailer may need to place a large order before a seasonal sales period. The cash outflow could occur before the related customer cash receipts arrive, creating a temporary gap even when the product is expected to sell well.
Review purchase orders, minimum order quantities, deposits, delivery timing, and vendor terms. For service businesses, the comparable items may be subcontractor fees, materials, or project-specific software and travel.
🏛️ Schedule Taxes as Cash Commitments
Tax obligations are not optional operating costs that can be estimated casually. Depending on the business and jurisdiction, cash outflows may include payroll taxes, sales or value-added taxes, income tax estimates, property taxes, and licensing fees.
Payment timing and rules vary substantially by location and entity type. Use the business’s actual filing calendar, notices, and advice from its qualified tax professional rather than relying on a generic schedule.
Set aside tax-related cash deliberately. Money collected from customers for transaction taxes may pass through the business bank account, but it is not freely available for inventory, owner draws, or expansion.
💳 Include Debt, Credit Cards, and Financing Costs
Debt payments need careful treatment because the total cash payment can include both principal and interest. For cash forecasting, include the entire amount leaving the account.
Credit card balances can create a similar trap. Purchases may have been made in prior months, but the cash leaves when the statement is paid. Record the expected payment date and distinguish minimum payments from the planned full balance payment.
Also include line-of-credit interest, loan fees, equipment financing, merchant cash advance repayments, and any required balloon payments. Read agreements for changing rates, seasonal payment terms, or covenant requirements.
🛠️ Treat Major Equipment Purchases Separately
Capital expenditures are purchases of long-lived assets such as vehicles, machinery, computers, fixtures, or major renovations. They are often too significant to bury inside ordinary monthly operating expenses.
Record the required deposit, expected delivery payment, sales taxes, installation costs, and financing arrangements. A purchase that appears affordable based on annual profit may still damage liquidity if its cash outlay arrives during a slow sales month.
Before committing, test alternatives: leasing, staging the purchase, buying used equipment, delaying a nonessential upgrade, or negotiating supplier terms. The right option depends on cost, reliability, tax treatment, and operating need.
👤 Make Owner Draws and Distributions Visible
Owner compensation is a real cash decision, whether it takes the form of payroll, drawings, distributions, or another legally appropriate mechanism. It should never be the unexplained difference between the bank balance and the bookkeeping records.
Forecast regular owner payments, planned distributions, and any expected personal reimbursement. If the business structure requires specific procedures or tax handling, follow professional advice.
Visibility supports better choices. An owner may decide to postpone a discretionary distribution after seeing an upcoming tax payment and a three-payroll month in the same forecast period.
🧱 Add a Cash Buffer, Not Just a Break-Even Balance
A forecast that ends each month at zero may be mathematically balanced but operationally fragile. Small delays, bank fees, returns, or an urgent repair can push it negative.
Set a minimum cash buffer based on the business’s volatility, payment obligations, access to credit, and management comfort. There is no single correct amount for every business.
The buffer should be treated as a decision threshold. When projected closing cash falls below it, the business has time to investigate, adjust spending, accelerate collections, or arrange financing before payments are missed.
➕ Calculate Monthly Net Cash Flow Clearly
Once receipts and disbursements are listed, total each group by month. Subtract total cash outflows from total inflows to find net cash flow.
A positive net cash flow means cash is expected to increase during that month. A negative number means the business will use cash. Neither result is automatically good or bad: a negative month may be planned because of inventory purchases or annual insurance.
The more useful question is whether the closing cash remains above the business’s required minimum after the planned movement occurs.
🔗 Roll Closing Cash Forward Month by Month
Forecasting is cumulative. A strong month in April can fund a planned May outflow, while a weak March can create pressure for several months afterward.
Use this sequence for each period:
- Start with the prior month’s closing cash.
- Add expected cash receipts.
- Subtract expected cash payments.
- Compare the resulting closing cash with the minimum buffer.
This rolling structure exposes timing problems that annual totals often hide. A business can have positive cash flow for the year and still run out of money in a particular month.
🌦️ Use Base, Upside, and Downside Scenarios
A single forecast can create false confidence when its assumptions are uncertain. Scenario planning asks how the cash position changes if important variables move differently than expected.
A base case uses the most reasonable operating assumptions. An upside case may include faster collections or stronger sales. A downside case might assume delayed customer payment, lower seasonal demand, a higher materials cost, or a missed sales target.
Do not create dozens of scenarios. Focus on the few drivers most likely to affect cash. For many businesses, collection timing, sales volume, gross margin, inventory purchases, and payroll are the most influential variables.
🚦Identify the Months That Need Action
Highlight any month where closing cash is projected below the buffer, not merely below zero. Then identify what causes the gap.
The cause may be temporary, such as an annual payment, or structural, such as recurring payroll consistently exceeding reliable collections. The response should fit the cause.
- For a short timing gap, negotiate a due date, accelerate a collection, or use pre-arranged short-term financing carefully.
- For a recurring gap, review pricing, margins, overhead, staffing, payment terms, or the business model itself.
- For a growth-driven gap, align financing with the asset or working-capital need rather than repeatedly improvising.
📞 Improve Collections Before Borrowing More
Late customer payment is a common source of avoidable cash strain. Before relying on more borrowing, examine the invoicing and collection process.
Send invoices promptly, confirm the correct billing contact and purchase-order details, state payment terms clearly, and follow up before—not only after—the due date. Offering suitable payment methods can also reduce friction.
Be thoughtful about discounts for early payment. A discount reduces margin, so it should be compared with the value of receiving cash sooner and the alternatives available to the business.
🤝 Negotiate Payment Timing With Suppliers
Supplier terms are a cash-flow lever, though not one to use carelessly. A supplier may be willing to align payment timing with delivery, accept staged payments for a large order, or offer longer terms after a reliable payment history is established.
Ask before a bill becomes overdue. A clear, early conversation is generally better for a supplier relationship than an unexplained missed payment.
Do not stretch payables as a permanent strategy. Chronic late payment can damage trust, trigger fees, interrupt supply, and conceal an underlying profitability or working-capital problem.
📈 Connect the Forecast to Sales and Operations Plans
A forecast should change when the operating plan changes. A new marketing campaign, large proposal, price increase, product launch, store opening, or staffing plan has cash implications beyond the headline decision.
For example, a campaign may require payment now but produce sales gradually. A forecast helps management ask whether the business can fund the gap and what level of sales conversion is needed for the plan to make sense.
This connection makes the forecast a decision model rather than a static finance document prepared after the fact.
🧹 Reconcile Forecast Results With Actual Cash
At the end of each month, compare the forecast with actual bank activity. Record actual opening cash, receipts, payments, and closing cash, then investigate meaningful differences.
A variance is the difference between expected and actual results. Useful questions include: Did customers pay later than expected? Was a supplier bill larger? Did sales settle in the next month? Was a planned purchase postponed?
The goal is not to blame someone for every variance. It is to improve the assumptions that drive future decisions.
🔁 Update the Forecast on a Routine Schedule
A forecast loses usefulness if it sits untouched while circumstances change. Many small businesses update it weekly for near-term items and perform a fuller monthly review after closing the books or reconciling bank accounts.
At each update, replace estimates for the completed month with actual results. Move open invoices and bills to their revised expected dates, add new commitments, and extend the forecast by another month.
Consistency matters more than complicated software. A simple forecast reviewed every week is usually more useful than a sophisticated model opened only once a quarter.
⚠️ Avoid Common Forecasting Mistakes
The most frequent errors are usually not calculation errors. They are assumptions that were never checked.
- Forecasting invoice dates instead of expected customer payment dates.
- Forgetting irregular costs such as annual renewals, repairs, taxes, and insurance.
- Using profit as a substitute for cash availability.
- Ignoring card settlement delays, debt repayments, or owner withdrawals.
- Assuming every planned sale will occur and every customer will pay on time.
- Failing to update the model when actual results differ from the plan.
A forecast becomes more credible when uncertainty is shown openly rather than hidden inside optimistic numbers.
🧠 Keep the Model Detailed Enough, but Not Overbuilt
Too little detail makes a forecast vague; too much detail makes it difficult to maintain. The best level depends on what decisions the business needs to make.
Separate items that have distinct timing or management significance, such as payroll, taxes, key suppliers, debt, and large customer collections. Group small, stable costs when separate tracking would add work without changing decisions.
Use clear labels and document important assumptions in notes or a separate tab. A manager should be able to understand where a number came from without rebuilding the spreadsheet from scratch.
🔐 Know When Professional Input Is Needed
A cash forecast supports management, but it does not replace legal, tax, lending, or investment advice. Professional input can be particularly valuable when the business is restructuring debt, facing tax arrears, raising equity, signing a major lease, or considering a transaction with long-term consequences.
An accountant or financial adviser can also help connect the forecast to financial statements, financing applications, and scenario analysis. The owner or manager still needs to understand the underlying assumptions, because they are closest to sales, customers, and operations.
🧩 Turn the Forecast Into a Monthly Management Habit
The strongest forecast is woven into routine business conversations. Review it before approving large spending, setting sales targets, committing to hiring, or deciding how much cash can be withdrawn.
A useful monthly meeting can cover expected collections, overdue invoices, large upcoming payments, changes in sales expectations, risks to the buffer, and specific actions with owners and due dates.
That rhythm transforms cash management from emergency response into regular operational discipline.
🏁 The Core Principle: Manage Timing, Not Just Totals
Monthly cash-flow forecasting works because it forces the business to see the sequence of cash movements. Annual revenue can look strong while a single badly timed month creates pressure; a planned cash dip can be manageable when it is visible early and funded appropriately.
Start with real opening cash, forecast collections and payments by date, include irregular obligations, maintain a buffer, and compare the plan with actual results. Then update the forecast often enough for it to influence decisions.
The aim is not an illusion of certainty. It is a practical, evidence-based view of what may happen next and enough lead time to respond intelligently.
A monthly cash-flow forecast gives a small business the ability to act before a cash gap becomes a crisis. Keep it current, challenge its assumptions, and use it whenever a meaningful financial decision is on the table. 💰📅📈